What Is Bust-Out Fraud? How Bust-Out Schemes Work and How Lenders Catch Them
ByTemitope Lawal
•5mins Read
Key Takeaways
A bust-out scheme builds good credit on purpose, then draws down every line at once with no plan to repay.
There are three types: synthetic identity, first-party and business credit bust-outs.
Bust-outs often get booked as credit defaults, which hides the real fraud losses.
The giveaway is credit stacking, a sudden spike in utilisation, and payments that bounce.
Prevention means stopping fake identities at onboarding and monitoring live accounts for the switch from quiet to spike.
For eighteen months, the account was perfect. Small balances, paid in full, never late. The lender raised the limit twice and pre-approved a personal loan. Then, over ten days, the card hit its limit, the loan was drawn, three new cards from other issuers maxed out alongside it, and every payment stopped. That is bust-out fraud, and most lenders do not see it until the money is already gone.
What makes it expensive is not the size of any single account. It is that the fraud looks like good credit behaviour right up to the last week, then gets booked as an ordinary default afterwards.
Below is how bust-out schemes are run, how to tell them apart from genuine defaults, and the signals that let you act before the drawdown.
What Is Bust-Out Fraud?
Bust-out fraud is a scheme where a borrower builds a good credit record on purpose, grows their credit limits, then draws down every available line at once with no intention of repaying. The "bust-out" is that final drawdown. Everything before it is preparation.
The bust-out fraud meaning is the same whether the borrower is a real person, a fake one or a business. What sets it apart from a normal default is intent: the borrower planned the loss from day one. That is why lenders treat it as fraud, even though it often ends up written off as bad debt.
Bust-out fraud is closely tied to synthetic identity fraud. A synthetic identity, a fake person built on a real Social Security number, is the ideal vehicle for a bust-out, because there is no real customer to chase once the money is gone.
How Does a Bust-Out Fraud Scheme Work?
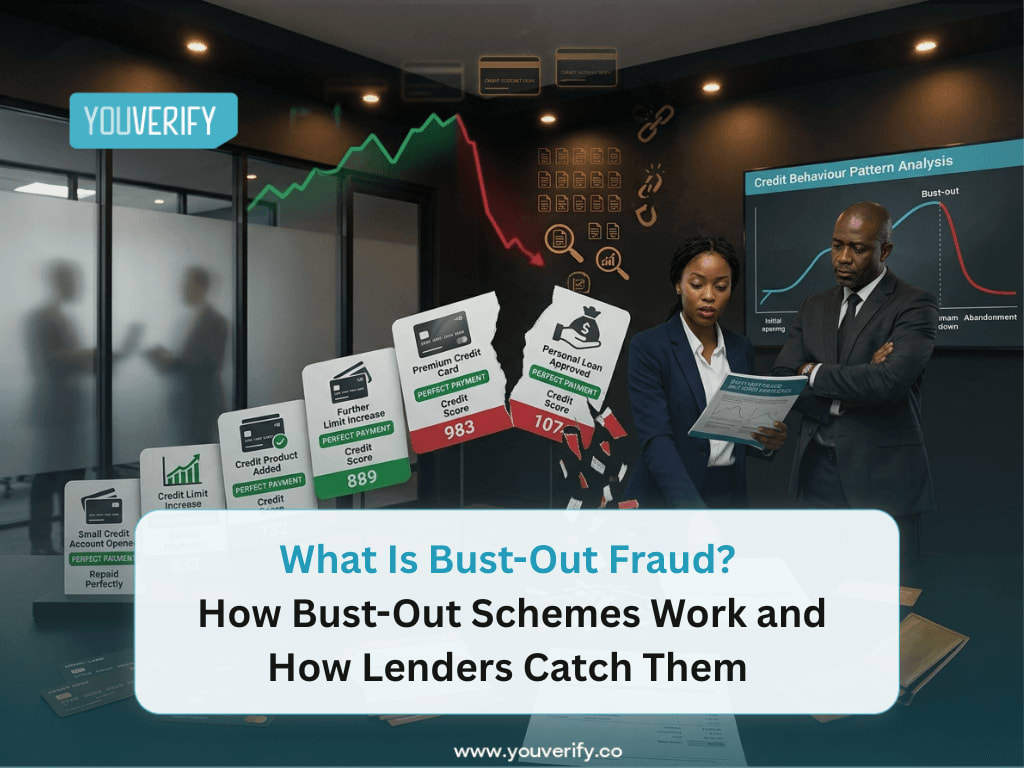
A bust-out scheme works in three phases: building trust, ramping up credit, and busting out. The first two can take months or years. The third usually takes days.
1. Building Trust: Small Credit, Perfect Payments
The fraudster opens a few modest accounts, often a retail card, a secured card or a small personal loan. They use them lightly and pay on time, every time. The goal is a clean file with a rising score, the profile every lender's model rewards.
2. Ramping Up Credit: Higher Limits Across More Lenders
With a strong record in place, the fraudster requests limit increases and applies to more lenders, often in a short window before new inquiries show up on every bureau report. Some add authorised-user tradelines from established accounts to push the score higher. By the end of this phase, the identity may hold tens of thousands of dollars in available credit spread across several institutions.
3. Busting Out: Draining Every Line at Once
At a planned moment, the fraudster maxes out everything: cash advances, balance transfers, convenience checks, and purchases of goods that resell easily, such as electronics and gift cards.
Many add a payment trick at the end. They send large payments from an account that will bounce, the lender restores the available credit before the payment clears, and the fraudster spends it again. When the payments return unpaid, the account is gone.
Some finish with credit washing: filing a false identity theft claim so the debts are removed from the credit file and the identity can be reused.
Phase
Typical length
What the lender sees
Building trust
6 to 24 months
A thin-file customer with flawless payments
Ramping up credit
Weeks to months
A good customer asking for more credit
Busting out
Days
A sudden spike, then silence
What Are the Types of Bust-Out Fraud?
Bust-out fraud comes in three main types: synthetic identity bust-outs, first-party bust-outs, and business credit bust-outs. The playbook is the same. What changes is who the borrower is.
1. Synthetic Identity Bust-Out: A Fake Person Busts Out
The borrower does not exist. Fraud rings build and age many synthetic identities in parallel, often linking them as authorised users on each other's accounts, then bust them out in waves. Collections has no one to find, so recovery is close to zero.
2. First-Party Bust-Out: A Real Customer Busts Out
A real person, using their own identity, runs up their credit with no plan to repay. This is a form of first-party fraud, and it is hard to prove because a real borrower can always claim they simply ran into money problems.
3. Business Credit Bust-Out: A Company Busts Out
A business, sometimes set up only for the scheme, builds trade credit with suppliers and lenders, orders as much stock as it can on credit, sells it off fast, and closes. This is the oldest form of bust-out scheme, long associated with organised crime, and it still shows up in business lending and B2B trade credit today.
4. Is Bust-Out Fraud the Same as a Credit Default?
Bust-out fraud is not the same as a credit default, even though the two can look identical in the books. The difference shows up in three places: intent, timing and spending pattern.
Factor
Genuine credit default
Bust-out fraud
Intent
Borrower meant to repay and could not
Borrower planned never to repay
Lead-up
Gradual strain: late payments, rising balances
Perfect payments until the final week
Spending before default
Essentials, bills, slow build-up
Cash advances, resellable goods, all at once
Other lenders
Often one or two accounts affected
Several lenders hit in the same window
Contact after default
Borrower can usually be reached
Phone, email and address go dead
This matters beyond fraud teams. When bust-outs are booked as credit losses, they inflate default rates, skew credit models toward approving the next fraudster, and hide the real size of the fraud problem from the board.
Why Is Bust-Out Fraud Growing in US Lending?
Bust-out fraud is growing for three reasons: instant digital credit decisions, cheaper synthetic identities, and losses that stay hidden as bad debt. In auto lending alone, Point Predictive's 2026 Auto Lending Fraud Trends Report found bust-out fraud has grown 67% over five years, according to Sovereign Magazine's coverage of the report, which lists it among the fastest-growing threats lenders face.
1. Instant decisions: Fully digital lending approves credit in minutes, which lets a fraudster open several accounts across lenders before any of them sees the others' inquiries.
2. Cheaper identities: AI tools now produce convincing ID documents and selfies, so building a synthetic identity that passes remote onboarding costs far less than it used to.
3. Hidden losses: A bust-out that is classed as a credit loss never triggers a fraud review, so the same pattern can repeat across a portfolio unnoticed.
What Are the Warning Signs of Bust-Out Fraud?
The warning signs of bust-out fraud are rapid credit stacking across lenders, a sudden utilisation spike after a long clean record, a shift toward cash-like spending, returned payments followed by fresh spending, and account detail changes just before the spike.
1. Credit stacking: Several new applications or accounts across different lenders within days or weeks.
2. Utilisation spike: Balances jump from low single digits to near the limit in a short window, with no history of heavy use.
3. Cash-like spending: Cash advances, balance transfers, convenience checks, gift cards and high-value electronics.
4. Payment Kiting: Large payments that restore available credit, followed by more spending, then the payments come back unpaid.
5. Detail changes: A new phone number, email or mailing address, or new authorised users added shortly before the spending starts.
No single signal proves a bust-out. A customer who just lost a job might max out a card too. The pattern is what gives it away: several of these signals at once, on an account that was perfect until now.
How Can Lenders Prevent Bust-Out Fraud?
Lenders prevent bust-out fraud in four ways: stopping fake identities at onboarding, tracking application velocity across channels, monitoring live accounts for behaviour shifts, and holding credit on unverified payments.
1. Stopping Fake Identities at Onboarding: Close the Front Door
Most bust-outs at scale run on synthetic identities. Verifying identity against authoritative data, and proving the applicant is a real, present person with document and liveness checks, removes the identities that bust-out rings depend on before they ever get a credit line.
2. Tracking Application Velocity: Spot the Stacking
Watch for the same device, phone number, email or address showing up across multiple applications in a short window. Fraud rings reuse infrastructure even when they change names, so device and session signals catch what identity data alone misses.
3. Monitoring Live Accounts: Catch the Shift From Quiet to Spike
Onboarding checks cannot see intent that forms later. Ongoing monitoring flags accounts whose behaviour changes sharply, such as a long-dormant or lightly used account that suddenly moves to cash advances and maximum utilisation.
4. Holding Credit on Unverified Payments: Shut Down Kiting
Do not restore available credit until a large or unusual payment has fully cleared. This one rule removes the payment kiting trick that turns a bust-out into a much bigger loss.
Catching Bust-Out Fraud Before the Drawdown With Youverify
Bust-out fraud is decided in two places: the day the identity is approved, and the week before the drawdown. Miss the first and you are funding a fraudster's credit-building phase. Miss the second and the loss lands all at once.
Customer Onboarding runs document, anti-deepfake liveness and government-source checks in one journey, scored to a risk tier, so synthetic identities built for bust-outs are stopped before they get a line. Fraud Insights scores device and browser fingerprint, IP spoofing, emulators, remote tools, velocity and behaviour inside the same session, which exposes the same ring applying under different names.
For accounts already on your books, Transaction Monitoring runs rules and models on live flows, so the sudden swing from quiet, perfect payments to cash advances and maxed limits gets flagged while there is still credit left to protect.
The next bust-out in your portfolio already has a clean payment history. Talk to our fraud team to see how Youverify spots it before the final week.
About the Author
Temitope Lawal is the Content Marketing Manager at Youverify, where she leads content on fraud prevention, AML compliance and identity verification. She has spent seven years turning complex financial crime topics into clear, practical guidance for the risk and compliance teams who have to act on them.
FAQs
Frequently Asked Questions
Credit washing is when a fraudster files a false identity theft claim to get debts removed from a credit file after a bust-out. If the dispute succeeds, the defaulted accounts disappear, the identity's score recovers, and the same identity can be used for another bust-out.
Yes. Bust-out fraud is a crime because the borrower takes credit with no intention of repaying. In the US, bust-out schemes are typically prosecuted under federal bank fraud, wire fraud or mail fraud laws, especially when they involve false identities or multiple lenders.
A bust-out scheme usually takes six months to two years from the first account to the final drawdown. The building and ramp-up phases take most of that time. The bust-out itself typically happens within a few days, so fraudsters can drain every line before lenders notice.
A credit bust-out is the final stage of a bust-out scheme, when the borrower maxes out every available credit line at once and stops paying. The term is also used as shorthand for the whole scheme of building credit in order to steal it.
The lenders most targeted by bust-out fraud are credit card issuers, auto lenders, personal loan and BNPL providers, and digital banks. Card issuers are popular because revolving credit can be drawn down fast, while auto lenders are targeted because one approval unlocks a high-value vehicle that can be resold.
Bust-out credit card fraud is a bust-out run mainly through credit cards. The fraudster builds a strong card history, collects limit increases and new cards from several issuers, then maxes them all out with cash advances, balance transfers and resellable purchases, often adding bounced payments to free up extra credit before disappearing.